Created With AI

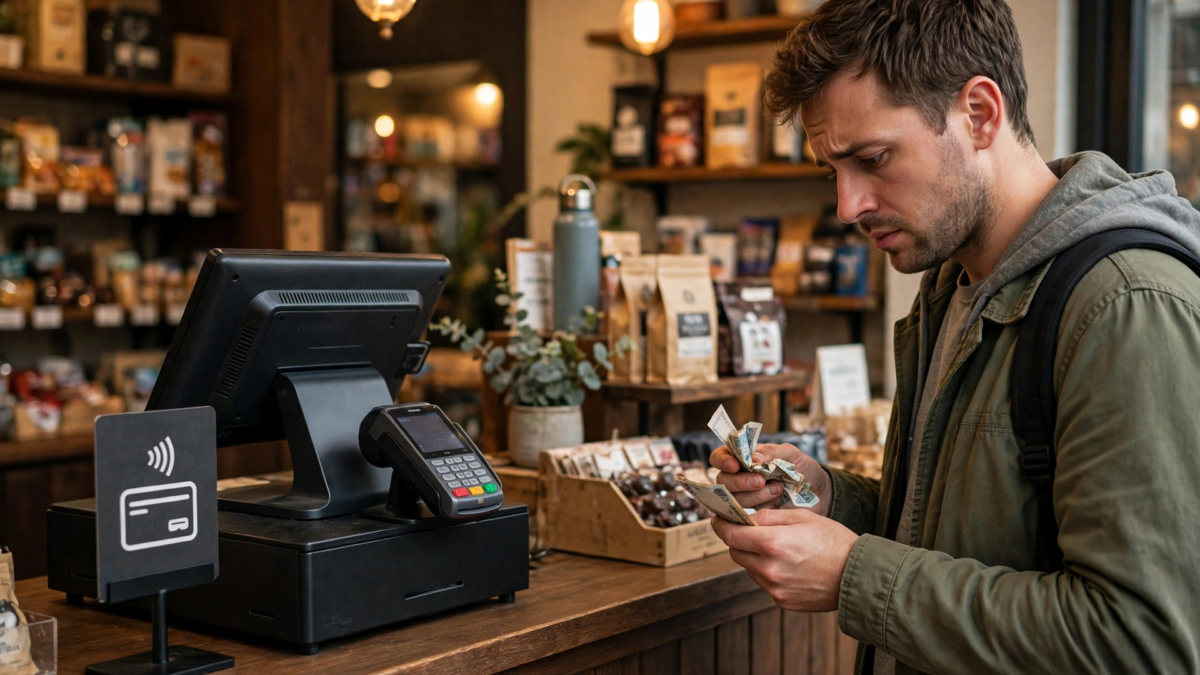
Picture a normal trip to the shops. You pick up bread and milk, walk to the till, and reach for your wallet. Then you see the sign. Card only. No cash accepted.

For many of us, that is a small annoyance. We tap a card or a phone and move on. For someone else, it can be the end of the trip. They may not have a bank card, or they may be trying to stick to a cash budget, or they may be an older neighbour who has always paid with notes and coins and never felt comfortable with a card reader.

That moment is why this debate has grown so heated. It is happening shop by shop, sign by sign. The question now is whether the law should step in before cash disappears from everyday life, or whether businesses should be free to choose how they get paid.

What would a cash protection law actually do?

A cash protection law would not have to mean that every seller must take cash for every sale. Laws already in place in some countries show how varied the idea can be.

In Norway, for example, a change to the Financial Contracts Act strengthened the right to pay with legal tender in shops that sell goods or services to consumers, with exceptions for unstaffed premises and vending machines. In Sweden, recent moves have pushed essential shops such as grocery stores and pharmacies to keep accepting cash. In other places, the protection looks different, focusing on access to cash itself, such as keeping ATMs within reach, rather than forcing every shop to accept it.

So when people say “protect cash by law,” they could mean essential shops must accept cash, banks must keep cash machines available, or a broader right to use cash for ordinary purchases. Those are not the same policy, and the debate gets clearer when we say which version we mean.

Grocery checkout with cash and card
Created With AI

First, a common misunderstanding about legal tender

Many people assume that because banknotes are legal tender, a shop must accept them. That is not how it works in everyday shopping, at least in the UK. Full Fact explains that it is completely legal for individual businesses to decline certain forms of payment, like cash or card, and the Bank of England says legal tender has a narrow technical meaning which has no use in everyday life. It mainly covers settling a debt, not buying bread at a till.

That surprises a lot of people, and it matters here. If we want shops to accept cash, we cannot rely on the phrase legal tender to do the work. We would need a new, clear law, with rules about which shops it covers and what happens if a shop breaks it.

The case for protecting cash by law

1. Cash keeps the door open for everyone

The strongest case for a law is about inclusion. Not everyone has a bank account, a card, or a phone that can pay. Some people are paid in cash, some live where banking services have closed, and some find a card reader hard to use while notes and coins in different sizes are easier to handle.

For those shoppers, a card only sign is not about preference. It is a closed door. Supporters argue that buying food and medicine should not depend on having the right piece of plastic or the right app. A law, in this view, is a simple guarantee that nobody is turned away at the till for paying the old fashioned way.

2. Cash helps people control spending and keep some privacy

Cash also has a practical appeal. When you pay with notes, you can see the money leave your hand. Many people say that helps them budget: they take out a set amount for the week, and when it is gone, it is gone. A card tap feels less real, and it is easier to lose track.

Privacy matters too. A card payment leaves a record, which can be useful when you need to prove a purchase or return something. But some shoppers would rather not have every coffee and pharmacy visit logged in a system. Cash lets them buy something ordinary without creating a trail, and supporters say that choice should be protected, not quietly removed as more shops go digital.

Hands counting banknotes
Created With AI

3. Cash still works when digital payments do not

Then there is resilience. Cards and phones need power, a signal, and a working system. Cash does not. When a card network goes down or a storm cuts power, cash keeps working in a way digital payments cannot. Supporters argue that keeping cash accepted in everyday shops is cheap insurance for the whole payment system.

Small shop accepting cash during a power cut
Created With AI

The case against a cash law

1. Businesses should be free to choose

The strongest case against a law is about freedom for businesses. Handling cash means keeping a till float, counting money at the end of the day, storing it safely, and getting it to a bank. That takes time and staff, and it carries a risk of theft or mistakes.

For a small cafe or market stall, going card only can be simpler and safer. Staff do not handle large amounts of cash late at night, the books are clearer, and the queue moves faster. Critics ask why such a business should be forced to keep a second system running by law.

2. A law could be hard to draw and hard to enforce

Critics also warn that a cash law sounds simple but gets messy in practice. Should it apply to a tiny online only business, a vending machine, or a shop with no safe place to store cash? Norway’s law includes exceptions, which shows lawmakers have to draw lines somewhere.

Enforcement is another question. If a shop puts up a card only sign, who checks, who complains, and what is a fair penalty for a small business that genuinely struggles with cash handling? A law that is not enforced may not change much, while a harshly enforced one could hurt the small shops it is meant to help.

3. Cash has real downsides, and digital payments have real benefits

Digital payments are popular for good reasons. They are fast and convenient, they make it easier to track spending or split a bill, and they reduce the risk of carrying large sums of cash. For many shoppers who rarely carry notes, a card only shop is not a problem at all.

Critics argue that a cash law could slow a shift most people actually want. They also point to crime and tax: cash can be harder to trace, which can make it easier to hide income, while digital payments leave a trail that can help catch fraud and make tax collection fairer. A law that forces cash acceptance, critics say, should not ignore those trade offs.

A balanced view

Both sides have a point, so the middle ground is worth a closer look. A law does not have to be all or nothing. It could focus on essentials first: food, medicine, fuel, and public services, where being turned away hurts most. It could pair acceptance rules with access rules, so people can actually get cash from an ATM, not just spend it in theory.

It could also allow sensible exceptions for very small sellers and unstaffed machines, and it could be reviewed over time, so the rules can change with how people really pay.

The key question is not whether cash is good and cards are bad, or the other way round. It is whether we want payment choice protected as a basic part of everyday life, or left entirely to each business. If we want choice, we need to say so in law, because the current legal tender rules do not guarantee it. If we want business freedom, we need to accept that some shoppers will be left out, and think honestly about who they are.

What do you think? Should essential shops be required by law to accept cash, should the law cover all shops, or should it stop at keeping ATMs available? And if your favourite shop went card only tomorrow, would it change how you shop? Share your view in the debate below.

Frequently asked questions

Does legal tender mean a shop must accept cash?
No, not for an ordinary purchase. In the UK, for example, a shop can choose what payment it accepts, and legal tender mainly covers settling a debt. That is why supporters argue a specific new law would be needed.

Would a cash law force every shop to take cash?
Not necessarily. Some laws focus on shops that sell to consumers, with exceptions for unstaffed premises and vending machines. Others focus on keeping access to cash, such as ATMs, rather than forcing acceptance everywhere.

Who benefits most from protecting cash?
People who do not have a bank card, people who budget with cash, older shoppers who prefer notes and coins, and anyone who needs a payment method that works without power or a signal. Those groups are the heart of the inclusion argument.

What is the alternative to a full cash law?
Common middle options include requiring cash acceptance only for essential shops, guaranteeing access to ATMs, allowing exceptions for very small or unstaffed sellers, and reviewing the rules as payment habits change.

Video

The Short below is a single sided argument for cash, not a balanced summary. The counterarguments are in the post above.

Why Europe Is Banning Cash, https://www.youtube.com/shorts/SJ8dXC0LM2A

Further reading

Discussion

Respectful, concise discussion is welcome. Focus on the data.

Join the discussion

Your email will not be published. Required fields are marked *